By LCN Business Desk
Everything said in public about this bank since it opened has given one number. The website gives two.
What are the two loans?
A Quick Loan of up to G$300,000 and an SME Loan of up to G$3,000,000.
Under the heading "OUR LOANS", the Bank's site sets out two products and tells applicants: "Both Loans Are Zero-Interest Financing, So You Repay Only What You Borrow."
| Quick Loan | SME Loan | |
|---|---|---|
| Borrow up to | G$300,000 | G$3,000,000 |
| Described as | "For Small Businesses" | "For Small And Medium Enterprises" |
| Named for | "Market Vendors, Salons, Barbershops, Food Sellers, Seamstresses, Mechanics And More" | "Agriculture, Agro-Processing, Manufacturing, Tourism, Services, Technology, The Creative Industries And More" |
| The application | "Short Application You Can Finish On Your Phone" | Details prefilled from your National ID record where available, and a list of how you will use the funds |
| Interest | Zero | Zero |
Source: gdb.gov.gy, read on 16 October 2026.
The Quick Loan asks an applicant to "Apply With A Short Description Of Your Business And What The Loan Is For". Both products offer the alternative of an appointment: "Prefer Help In Person? Book An Appointment With GDB".
Why does the second tier matter?
Because a market vendor and a manufacturer were being quoted the same figure.
The figure in circulation since the Bank opened has been G$3 million. It appears in the President's message in the Government's 5 October spread, in the messages of three ministers in the same document, and in the banner across the Bank's own home page, which reads "Now Accepting Applications, With Zero-Interest Financing Up To G$3,000,000."
That is the ceiling of the larger product. The capital the Bank has to lend against both ceilings was set out in G$20 Billion to Lend and a G$3 Million Ceiling.
A seamstress or a barber reading the G$3 million figure is reading the wrong product. The one built for that trade is the Quick Loan, at up to G$300,000, which the Bank says can be completed on a phone.
What does the Bank charge?
Nothing. The site states it three ways.
The loans are zero interest. The site's own repayment estimator puts the point plainly: for an illustrative G$250,000 borrowed over 24 months it shows a monthly instalment of G$10,417 and interest of G$0. That is the principal divided by the term and nothing added.
The estimator offers terms of 6, 12, 18 and 24 months, with a slider marked at G$50,000, G$300,000 and G$3,000,000. It carries its own warning: "Illustrative Only. Your Final Amount, Term And Instalment Are Set In Your Letter Of Offer."
Who is the Bank, in its own words?
A government institution under the Ministry of Finance.
The site describes the Bank as "A Government Of Guyana Institution Under The Ministry Of Finance, Serving Small And Medium Businesses", under the heading "A Bank Built For The Businesses That Develop Guyana". Its pages carry the coat of arms and a government banner linking to the Ministry of Finance.
It also carries a line from the President: "You Don't Have To Own Anything. You Just Have To Have An Idea That We Will Help You Develop, That We Will Help You To Nurture."
Which of the four accepted documents is attached to a register, and what it does and does not hold, is set out in The Card That Takes You to Barbados Is Also the One the Development Bank Can Read. Who sits on the board that will apply these terms is set out in Guyana's Development Bank Has Seven Directors, and the Act that created it in The Guyana Development Bank Act Is in Force.
Can everyone read this?
Not from outside Guyana.
What an applicant must have in hand, and the four steps from applying to being paid, are set out in What You Need Before You Apply and From Application to Money in the Account. The Bank restricts its website to visitors in the country, which was tested and reported in The Development Bank's Website Stops at Guyana's Border. A reader in Guyana opening gdb.gov.gy sees the two products set out above. A reader abroad sees a notice of eligibility.
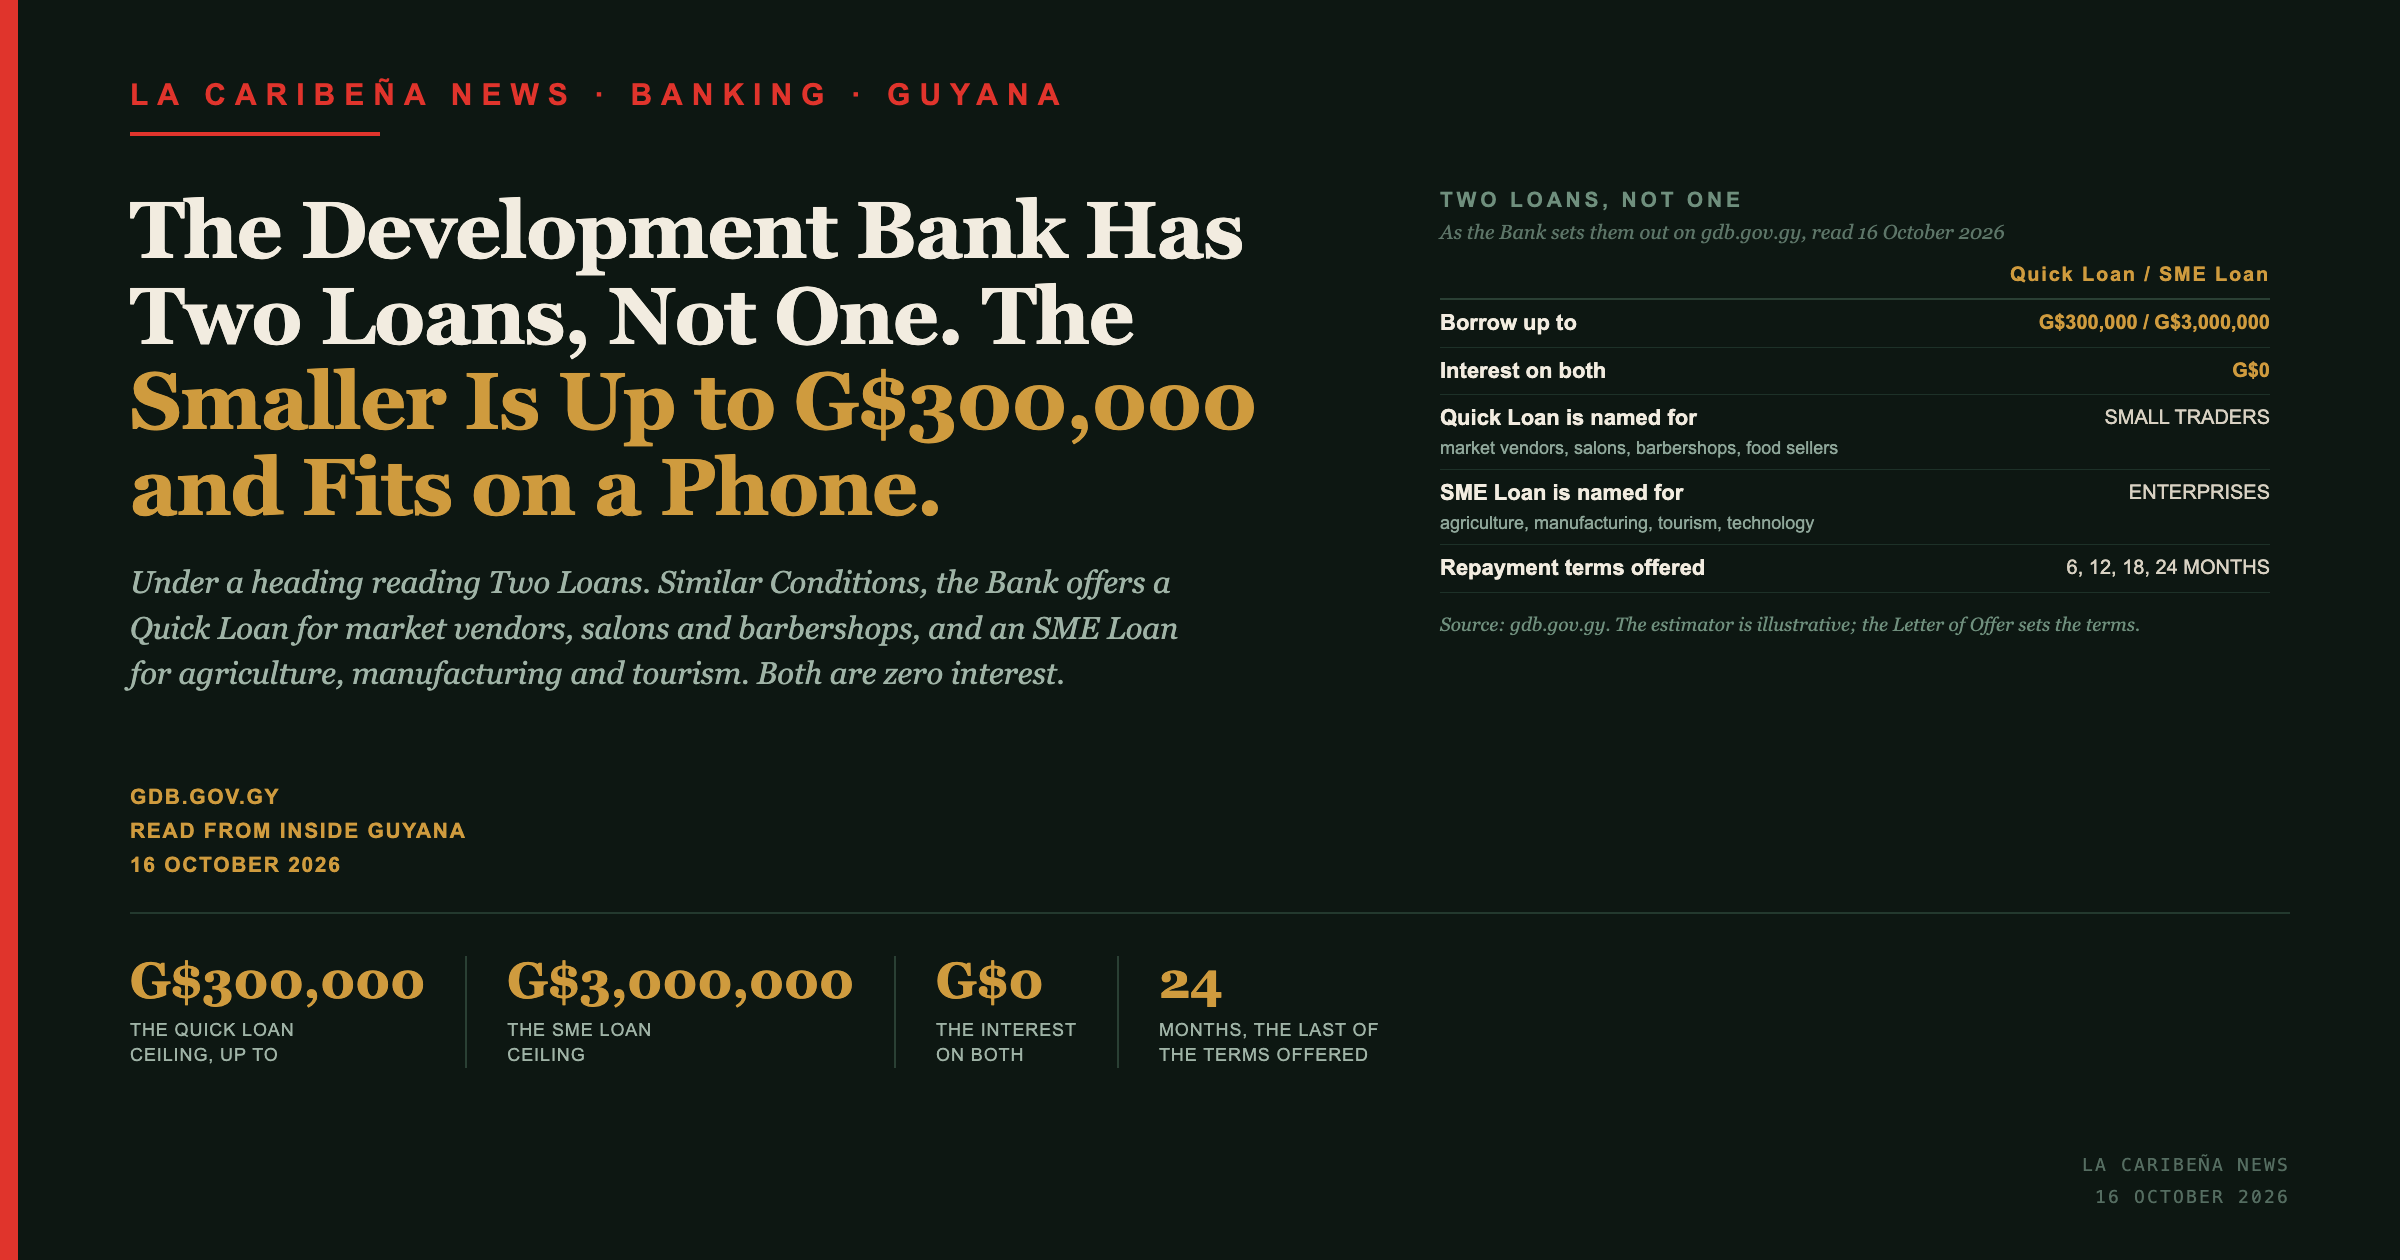
What the title card shows
Every data point on the article's title card, in text.
- 2 loans. The products the Bank's site sets out under "Two Loans. Similar Conditions."
- Up to G$300,000. The Quick Loan ceiling, for market vendors, salons, barbershops, food sellers, seamstresses and mechanics.
- G$3,000,000. The SME Loan ceiling, for agriculture, agro-processing, manufacturing, tourism, services, technology and the creative industries.
- G$0. The interest on both, and the figure the Bank's own estimator returns.
- 6 to 24 months. The repayment terms the estimator offers, at 6, 12, 18 and 24.
Frequently Asked Questions
How many loans does the Guyana Development Bank offer?
Two. A Quick Loan of up to G$300,000 and an SME Loan of up to G$3,000,000, set out on gdb.gov.gy under the heading "Two Loans. Similar Conditions."
Which loan is for a market vendor or a salon?
The Quick Loan. The site names market vendors, salons, barbershops, food sellers, seamstresses and mechanics, and describes a short application that can be finished on a phone.
Which loan is for a manufacturer or a farm?
The SME Loan, which the site associates with agriculture, agro-processing, manufacturing, tourism, services, technology and the creative industries.
What interest is charged?
None on either product. The site's repayment estimator shows interest of G$0, and states that both loans are zero-interest financing so a borrower repays only what was borrowed.
How long is the repayment term?
The estimator offers 6, 12, 18 and 24 months, and states that the final amount, term and instalment are set in the applicant's Letter of Offer.