By LCN Business Desk
The figure an applicant picks on the Bank's own calculator is not the figure they get. The Letter of Offer decides that.
What are the four steps?
Apply, review, accept, disburse.
Under a heading reading "From Application To Money In Your Account", the Bank's site numbers the process.
| Step | What the Bank says happens |
|---|---|
| 1. Apply Online | "Complete Your Application Online. Your Details Are Prefilled From Your National ID Record Where Possible." |
| 2. Review | "A GDB Credit Officer Reviews Your Application. You Will Be Notified If Additional Information Is Required." |
| 3. Accept Your Offer | "Receive A Letter Of Offer With The Amount, Term And Instalment. The Letter Of Offer Is Accepted And Signed Online." |
| 4. Loan Disbursed | "Your Loan Is Paid Into Your Bank Account. Repay As Per Your Instalment Cycle, With No Interest." |
Source: gdb.gov.gy, read on 16 October 2026.
What an applicant must have in hand before step one was set out in What You Need Before You Apply.
What does the Letter of Offer decide?
Three things, and they are the three an applicant cares about.
The Letter of Offer carries the amount, the term and the instalment. It is accepted and signed online, so acceptance is a step the applicant takes rather than a formality that happens to them.
The Bank's own repayment estimator carries the same point as a warning: "Illustrative Only. Your Final Amount, Term And Instalment Are Set In Your Letter Of Offer."
An applicant who sets the estimator to a figure and plans around it is planning around an illustration. The three numbers that bind arrive at step three.
What does the estimator show?
Principal divided by the term, and nothing added.
The estimator asks "How Much Does Your Business Need?" with a slider marked at G$50,000, G$300,000 and G$3,000,000, and offers repayment over 6, 12, 18 or 24 months.
For an illustrative G$250,000 over 24 months it returns a monthly instalment of G$10,417 and interest of G$0. G$250,000 divided by 24 is G$10,416.67, so the instalment is the principal spread across the term with nothing added, rounded to the dollar.
The two products the estimator covers, and their ceilings, were set out in The Development Bank Has Two Loans, Not One.
What happens at the review step?
A credit officer reads it, and may come back for more.
Step two puts a GDB credit officer between the application and the offer, and the Bank says an applicant "Will Be Notified If Additional Information Is Required". An application is therefore not a form that passes or fails on submission, and an applicant should expect to be reachable on the phone number given at registration.
Which of the four accepted documents is attached to a register, and what it does and does not hold, is set out in The Card That Takes You to Barbados Is Also the One the Development Bank Can Read. The Bank lends without collateral, which places the weight of the decision on that assessment rather than on security. The board that sits above the credit function is set out in Guyana's Development Bank Has Seven Directors, and the capital it lends against in G$20 Billion to Lend and a G$3 Million Ceiling.
When does the money move?
At step four, into a bank account.
The loan is paid into the applicant's bank account, and repayment runs on an instalment cycle with no interest. Bank details must be provided before disbursement, which is why that item appears on the requirement list for both products.
The Bank's site is open only to visitors in Guyana, reported in The Development Bank's Website Stops at Guyana's Border, so an applicant abroad cannot run any of these steps from where they are.
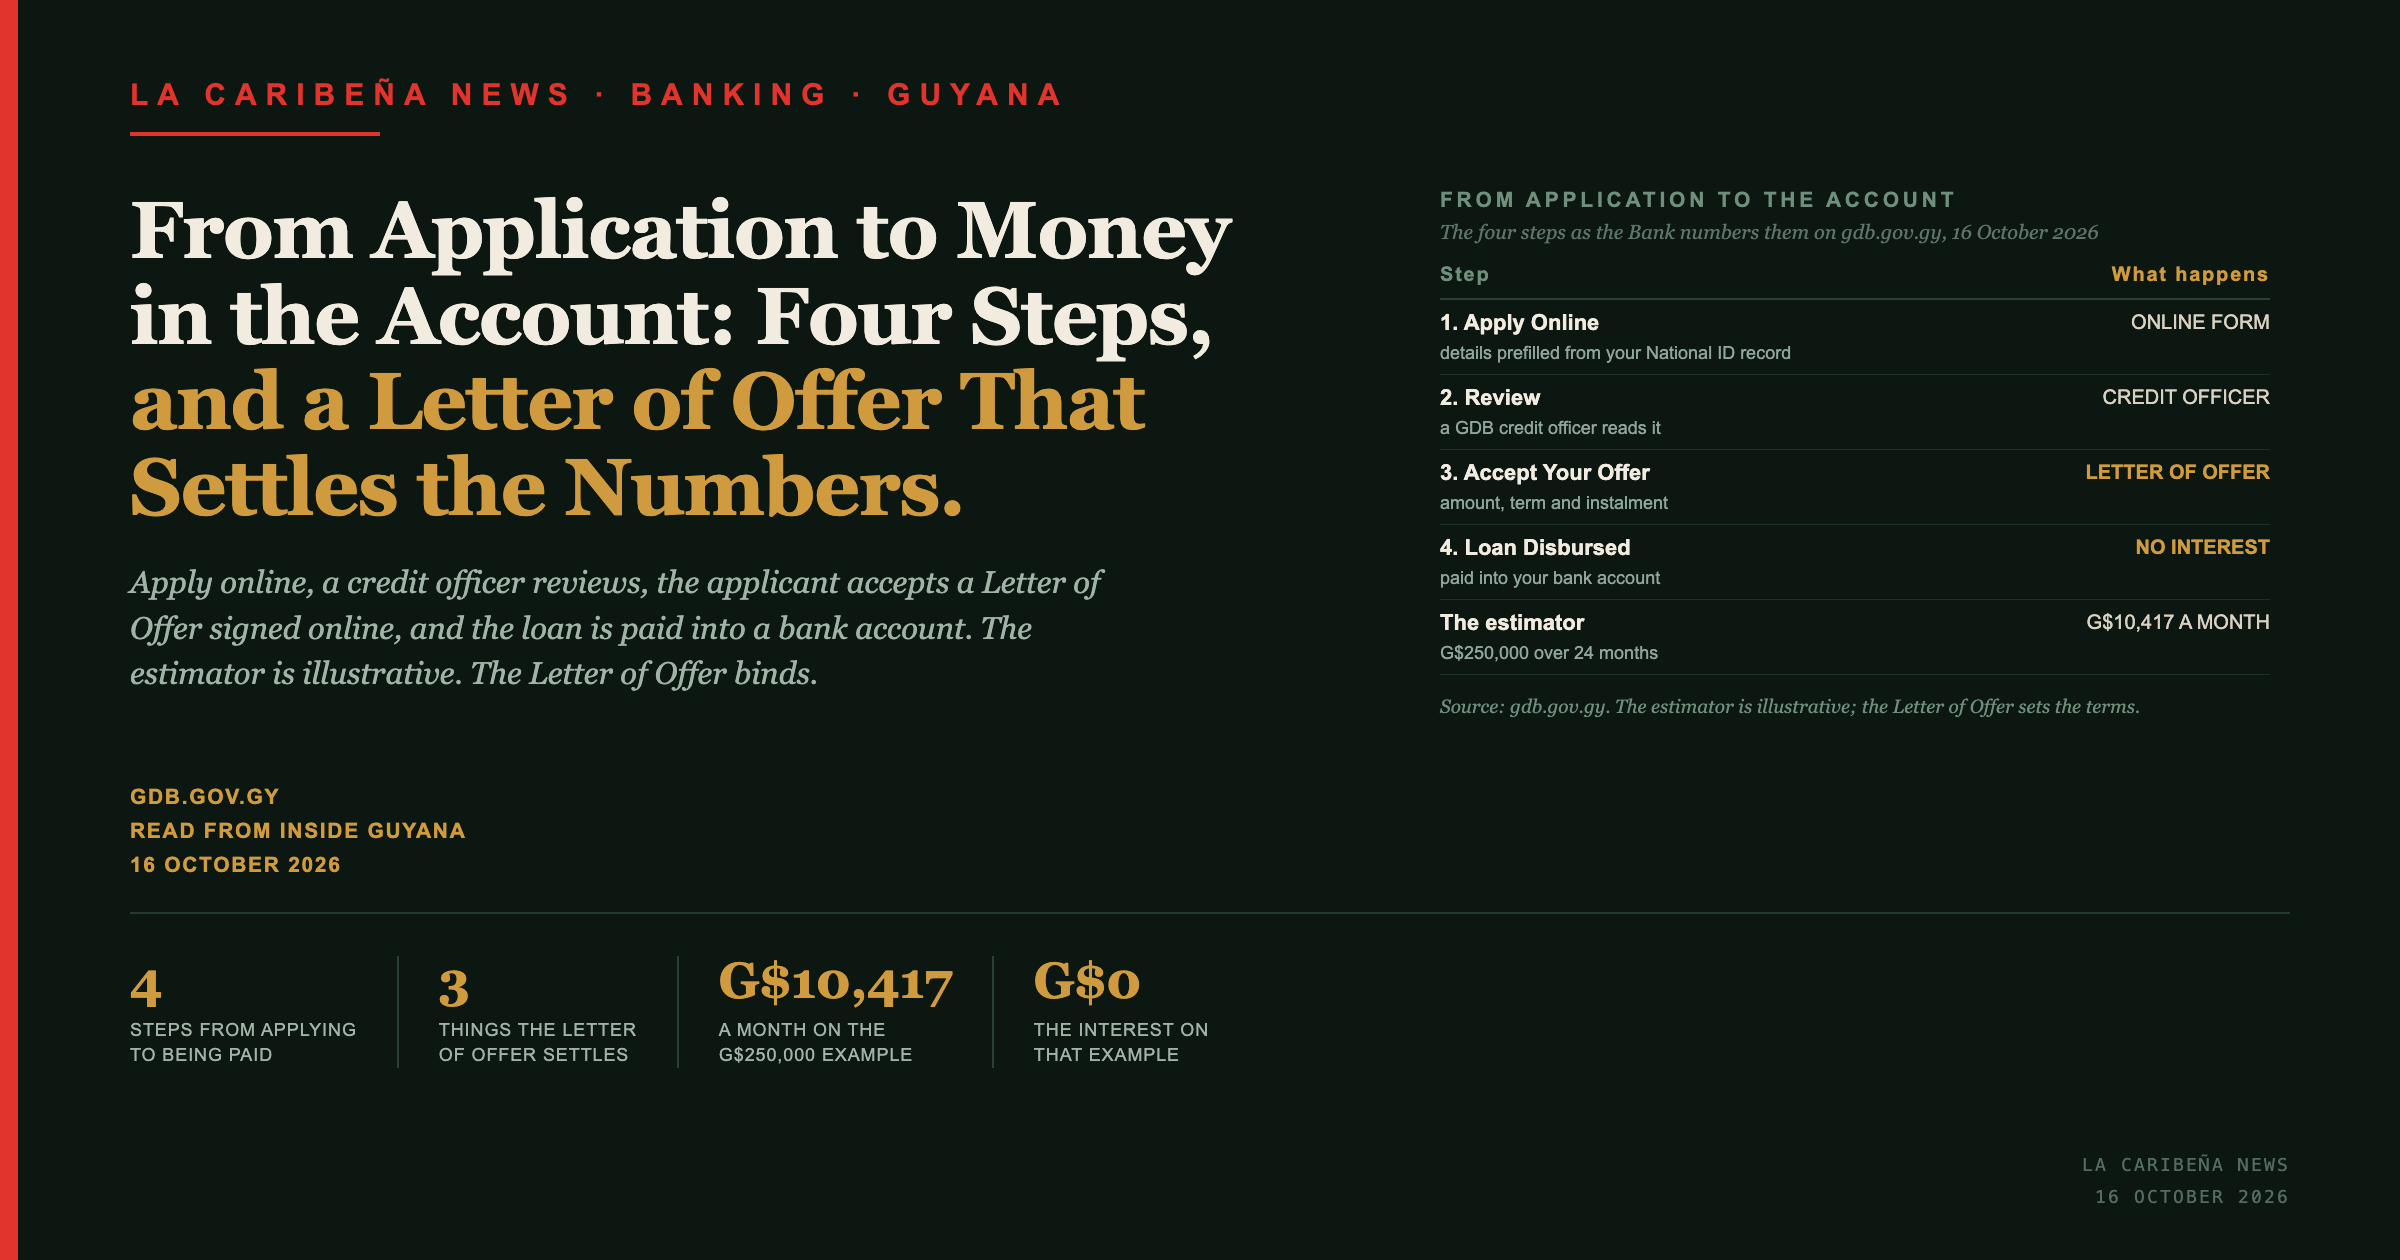
What the title card shows
Every data point on the article's title card, in text.
- 4 steps. Apply online, review by a GDB credit officer, accept the Letter of Offer, loan disbursed.
- 3 things in the Letter of Offer. The amount, the term and the instalment, accepted and signed online.
- 6, 12, 18, 24 months. The repayment terms the Bank's estimator offers.
- G$10,417. The monthly instalment the estimator returns for an illustrative G$250,000 over 24 months.
- G$0. The interest the estimator returns on that example.
Frequently Asked Questions
What are the steps to get a loan from the Guyana Development Bank?
Four. Apply online with details prefilled from your National ID record where possible; a GDB credit officer reviews the application and notifies you if more information is required; you receive a Letter of Offer with the amount, term and instalment, and accept and sign it online; the loan is paid into your bank account.
What does the Letter of Offer contain?
The amount, the term and the instalment. It is accepted and signed online.
Is the repayment estimator binding?
No. The site states it is illustrative only and that the final amount, term and instalment are set in the Letter of Offer.
How are repayments calculated?
With no interest. For an illustrative G$250,000 over 24 months the estimator returns G$10,417 a month, which is the principal divided by the term.
How is the money paid out?
Into the applicant's bank account. Bank details must be provided before loan disbursement.