By LCN Business Desk
The Partnership for National Unity said at its weekly press briefing on Friday 26 September that it supports the Guyana Development Bank's objectives and objects to the way the President proposes to make its lending public, Guyana Times reported. The bank begins processing applications on 5 October, reported in The Guyana Development Bank Act Is in Force.
What is APNU asking for?
The party wants the naming of applicants dropped. President Irfaan Ali said on 20 September that people selected for loans would be publicly identified before receiving financing, with one or two weeks for the public to object, reported in Guyana Plans to Name Its Development Bank Borrowers Before They Are Paid.
APNU said that proposal has to be reconciled with the legislation the President signed. The Act treats information obtained by the bank as confidential and to be used solely for carrying out its functions, subject to disclosure where required by law. "There is, therefore, an obvious proposed policy removal required by the Government to ensure compliance with its own Development Bank Act," the party said.
Transparency in the management of public funds does not require exposing the personal financial affairs of individual citizens, the party said. In place of names it proposed that the bank publish the sectors being financed, the geographic distribution of loans, repayment performance, default rates, approval criteria, related-party transactions and developmental outcomes. Applicants should also be told, before they apply, what confidentiality protections they hold and what may be disclosed.
What has the opposition asked for since the Bill appeared?
APNU parliamentarian Dr Terrence Campbell called the Bill "a recipe for disaster" on 13 June, two weeks after it was gazetted, and asked for it to go to a Select Committee, Kaieteur News reported. He wanted an opposition nominee on the board, penalties for officials who corruptly demand favours to grant loans, and stated qualifications for the chief executive. He also noted that the bank sits outside the Financial Institutions Act.
People's National Congress Reform leader and APNU chairman Aubrey Norton said on 1 September that the party would table amendments, and that what had passed "looks like a slush fund that the PPP can use to give PPP people what they want", Kaieteur News reported. Campbell's list by then took in the G$3 million ceiling, which he called useful to a micro-enterprise and not transformative for a genuine small business, since a firm employing 25 people at the G$60,000 private-sector minimum wage pays out half of it in a single month of salaries. He asked for an independent credit committee, Bank of Guyana oversight rather than the Auditor General alone, and mandatory annual reporting on loans issued, jobs created, geographic distribution and non-performing loans.
The Leader of the Opposition, Azruddin Mohamed of We Invest in Nationhood, said on 16 September that the bank was being launched without key safeguards, Kaieteur News reported. Every director is appointed by the Minister, five to nine of them including the chairperson and deputy, with no National Assembly approval. He cited Germany's KfW, where Parliament appoints seven members of the supervisory board and has included opposition nominees, Malta's development bank, which requires consultation with the opposition before either chairperson is appointed, and South Africa's Land Bank, where parliamentary committees may nominate candidates.
Mohamed's other objection was to the penalties. "For serious insider corruption, a fine without express provision for imprisonment, confiscation, or permanent disqualification risks becoming little more than a tap on the wrist," he said. "Nor does the legislation establish a protected complaints mechanism or independent investigation process."
What does the Act say about offences?
Section 33(1) makes it an offence to provide false or misleading information to the bank, to obstruct it, to falsify, conceal, alter or destroy a record relating to its affairs, to improperly disclose confidential information, or to wilfully misapply or misuse its funds, property or assets.
| Offence under section 33(1) | Penalty on summary conviction |
|---|---|
| Providing false or misleading information | G$5m to G$10m fine |
| Obstructing or hindering the bank | G$5m to G$10m fine |
| Falsifying, concealing, altering or destroying a record | G$5m to G$10m fine |
| Improperly disclosing confidential information | G$5m to G$10m fine |
| Wilfully misapplying or misusing the bank's funds | G$5m to G$10m fine |
Section 33(2) applies the same range to every limb, on summary conviction, and prescribes no custodial penalty. Section 33(4) extends liability to a director, manager or secretary where a body corporate offends with their consent or connivance, or through their neglect.
The floor for misdirecting the bank's funds is therefore the floor for filling in a form wrongly, which is the disproportion Mohamed identified. The Act also creates no offence of soliciting or accepting a benefit in return for approving a loan, which Campbell raised in June.
How much of this needs Parliament?
Section 34 empowers the Minister to make regulations on the operations of the bank, on the terms and conditions applicable to its loans and on recovery. Section 25 requires the board to adopt written credit policies covering eligibility criteria, risk assessment, approval thresholds, and monitoring and recovery. Section 12 allows the board to establish committees. The reading of the statute is set out in What the Guyana Development Bank Act Requires.
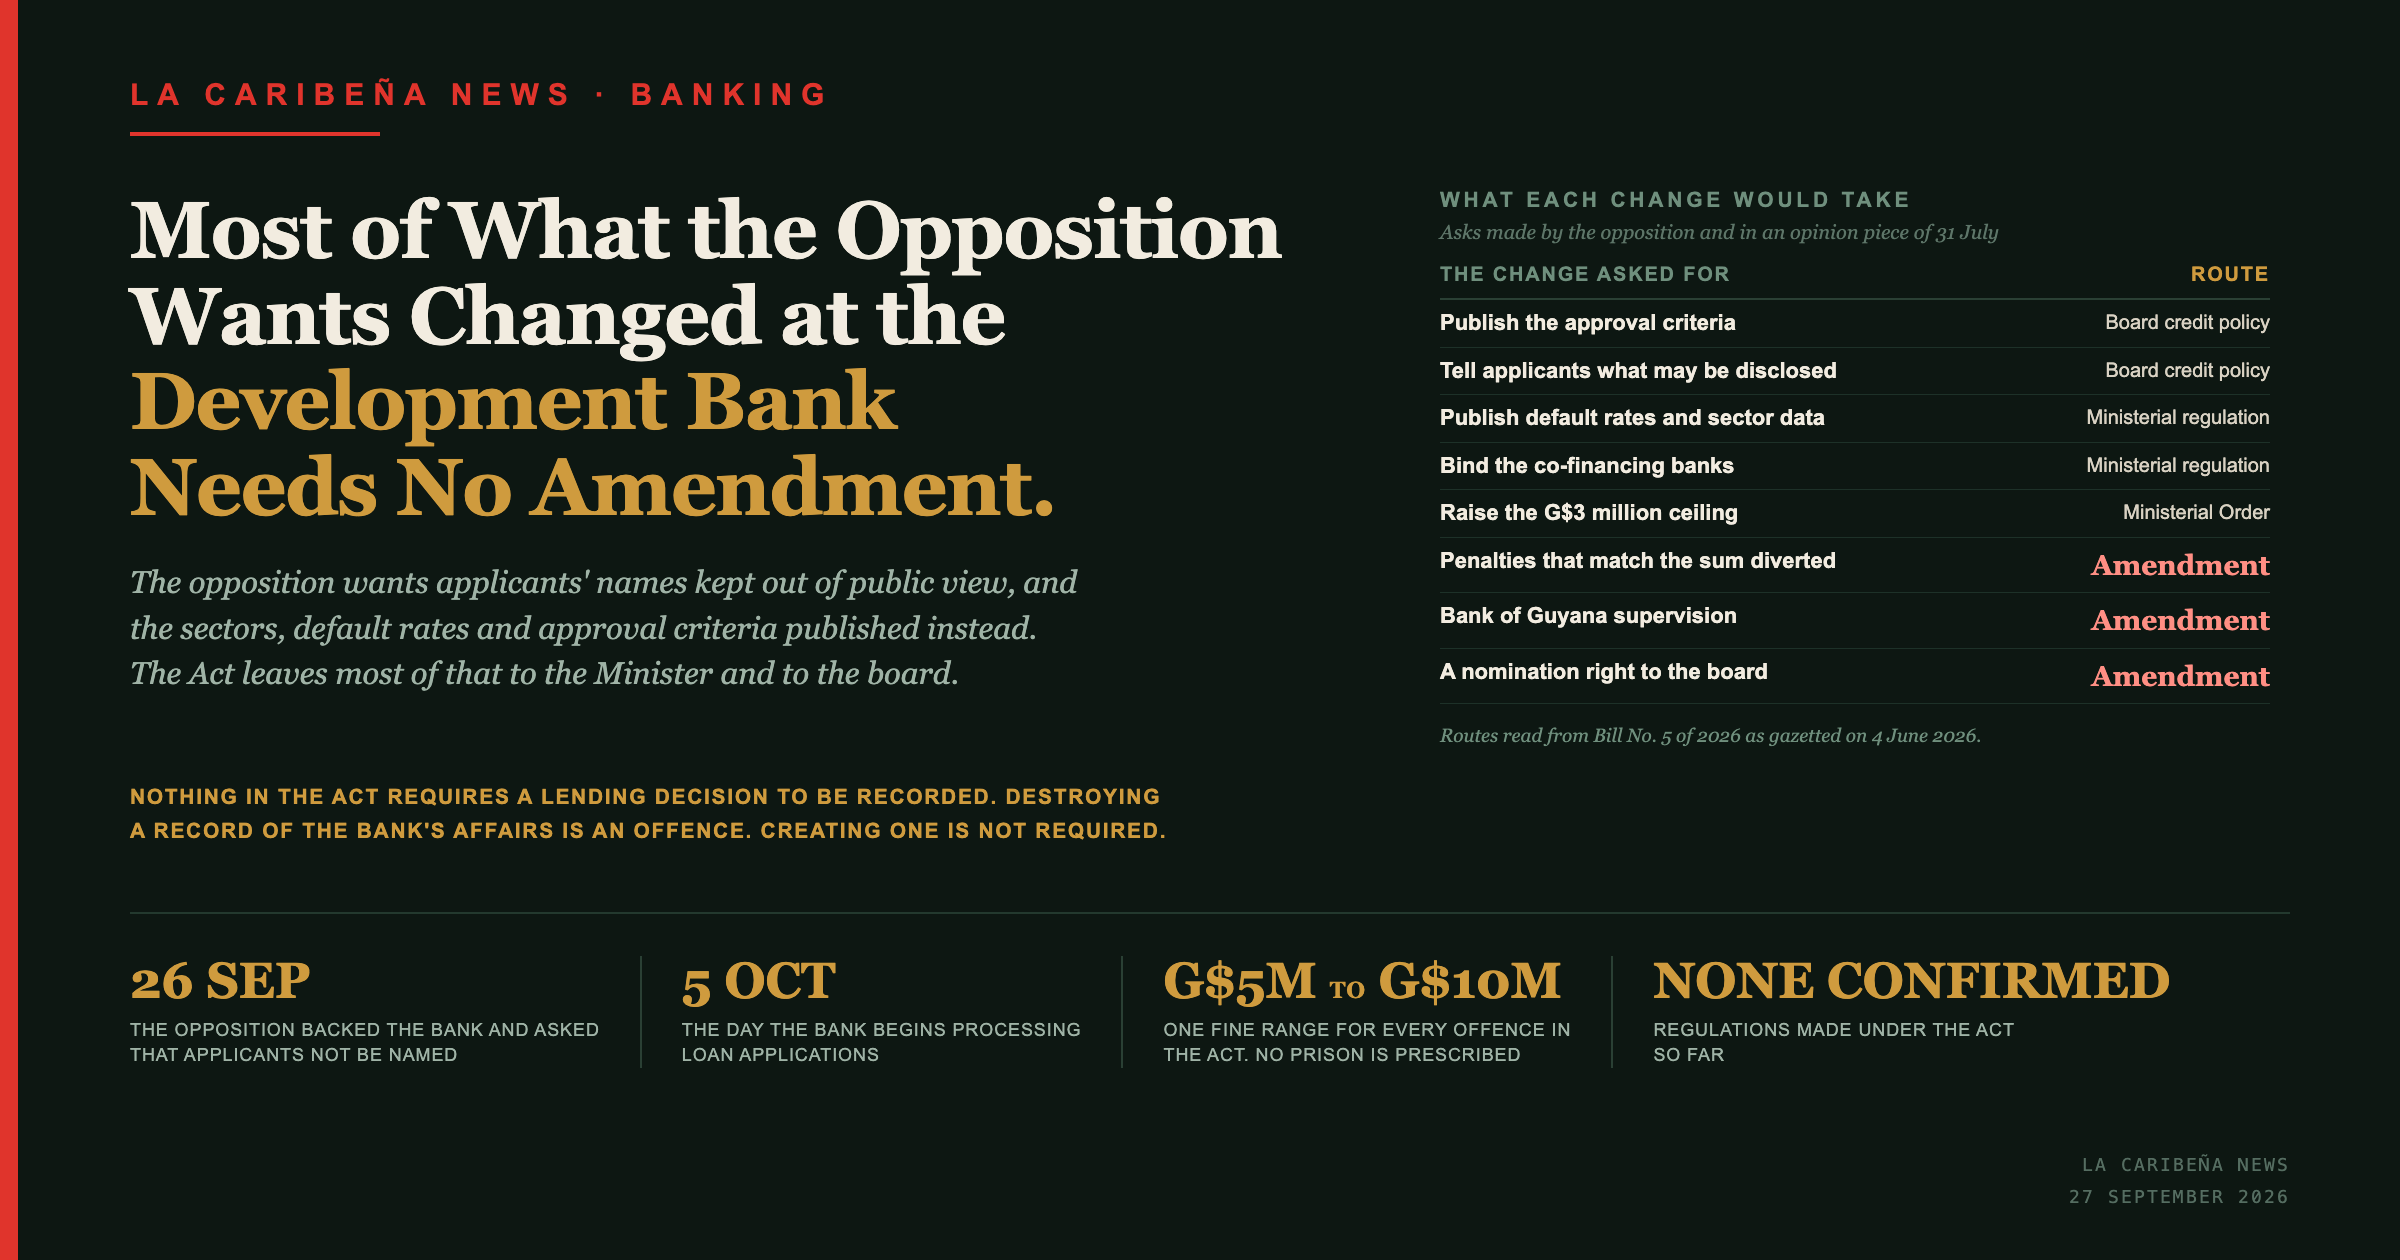
| Ask | Raised by | Route |
|---|---|---|
| Publish the approval criteria | APNU 26 Sep; opinion piece 31 Jul | Board credit policy, or regulation |
| Publish sector, geographic and default data | APNU 26 Sep; Campbell 1 Sep | Regulation |
| Publish developmental outcomes and jobs created | APNU 26 Sep; Campbell 1 Sep | Regulation |
| Disclose related-party transactions | APNU 26 Sep | Regulation |
| Tell applicants in advance what may be disclosed | APNU 26 Sep | Board credit policy |
| Written reasons for a decline | Opinion piece 31 Jul | Board credit policy, or regulation |
| An appeals route outside the deciding office | Opinion piece 31 Jul | Board credit policy, or regulation |
| An independent credit committee | Campbell 1 Sep | Already permitted: the board may establish committees |
| Bind the co-financing banks to the same terms | Opinion piece 31 Jul | Regulation and the co-financing agreements |
| Raise the G$3 million ceiling | Campbell 1 Sep | Ministerial Order, negative resolution |
| A clearer definition of a medium-sized enterprise | Campbell 1 Sep | Ministerial Order, negative resolution |
| Penalties proportionate to the sum diverted, with prison | Mohamed 16 Sep | Amendment to section 33 |
| An offence of soliciting a benefit to approve a loan | Campbell 13 Jun; Mohamed 16 Sep | Amendment to section 33 |
| Bank of Guyana supervision of lending conduct | Campbell 13 Jun; Mohamed 16 Sep | Amendment: section 32 disapplies the Financial Institutions Act |
| A nomination right to the board | Campbell 13 Jun; Mohamed 16 Sep | Amendment to section 7 |
The highlighted rows are the ones that need the National Assembly. The rest sit with the Minister or the board. No regulations have been confirmed as made under the Act, and the bank opens on 5 October either way, so the first applicants will be assessed against whatever exists on that date.
Does the confidentiality clause block either side?
Section 31 treats information obtained by the bank as confidential and used solely for its functions, "except where disclosure is required by law". APNU's own statement records that carve-out. A regulation made under the Act is law, so the clause does not by itself stop the naming proposal, and it does not stop APNU's disclosure framework either. Nothing has yet been made under it.
Guyana's Data Protection Act 2023 is not in force, no commencement order having been issued, and the Data Protection Office was still being established as of May. Creditinfo's purchase of the country's credit bureau in August put borrower reporting in new hands over the same period, covered in Guyana's Credit Bureau Opened as Creditinfo in 2013.
Can the disclosure framework be delivered under the Act as drafted?
Default rates, repayment performance, approval criteria and developmental outcomes are reports about decisions. Nothing in the Act requires a decision to be recorded.
Section 23 governs what the applicant must submit. It sets no assessment standard and imposes no duty to give reasons for a refusal. Part VI covers accounts, audit and reporting, and its obligations are financial: the Auditor General audits the accounts, and the Minister lays the annual report. No provision requires the bank to record, retain, aggregate or publish how many applications it received, how many it declined, or why.
Section 33(1)(c) makes destroying a record of the bank's affairs an offence, and no provision requires one to be created. Section 9(c) obliges the board to safeguard the independence of credit decisions, and attaches no record, no report and no consequence to that duty.
An audit of the accounts does not answer whether two branches approved at different rates. Georgetown has not missed its audit deadline, set against a region where four years of audits went unpublished, in Santo Domingo Will Publish Four Years of Audits.
Where does the larger share of the money sit?
The headline offer is G$3 million from the bank paired with up to G$7 million from a commercial bank, set out in Guyana Development Bank Pairs G$3M Loans With G$10M Commercial Co-Financing. The Act reaches that second tier through a power to co-finance or collaborate with commercial banks, financial institutions or development partners, and attaches no amount, no rate and no obligation to it, examined in Seventy Per Cent of the Development Bank Package Sits at a Counter the Act Barely Reaches.
A disclosure regime written for the bank therefore covers the smaller share of the package. An applicant referred on to a commercial lender leaves the regime at that door, and none of the proposals on the table follows her through it.
What happened when the Bill went through?
The Bill was gazetted on 4 June and passed on 27 July without debate. The opposition was staging an in-house protest calling for two ministers to resign over the MV Barima, whose wreck is now itself the subject of a tender, reported in Three Firms Bid to Raise the MV Barima. The President assented on 30 July and the commencement Order was gazetted on 17 September.
The amendments Norton says his party will table cover the ground a committee stage would have covered, and arrive with the Act in force and the doors about to open. The substance of the asks has not changed since June.
How do the positions compare?
An opinion piece published on 31 July asked the bank to publish the credit policies the Act requires it to write, to give written reasons for every decline citing the criterion that failed, to provide an appeals route outside the deciding office, to write equivalent terms into the co-financing agreements, to publish outcome data by branch, region, sector, loan size and reason for decline, and to train officers against the published criteria with documented completion, in Write the Rules Down Before the Doors Open.
APNU's framework overlaps on the criteria and on outcome data. It adds related-party transactions and advance notice to applicants. It does not ask for written reasons for a decline, an appeals route, terms binding the co-financing tier, or training against the criteria. On the naming proposal the two positions arrive at the same place: a published list records who was chosen, and the criteria record why.
What the title card shows
- 26 September 2026: the date of the APNU press briefing backing the bank's objectives and objecting to the naming of applicants before approval. Source: Guyana Times.
- Routes to each reform: which of the asks on the table can be delivered by ministerial regulation or Order, which by the board's own credit policy, and which require an amendment to the Act.
- G$5m to G$10m: the fine range section 33(2) applies to every offence in section 33(1), from providing false information to wilfully misusing the bank's funds. No custodial penalty is prescribed.
- 5 October 2026: the day the bank begins processing applications. No regulations have been confirmed as made under the Act.
- G$3m and G$7m: the bank's own loan and the commercial co-financing beside it, the second reached by a power that attaches no amount, rate or obligation.
Frequently Asked Questions
What is APNU asking the Government to change?
To withdraw the proposal that loan applicants be publicly named before approval, which the party says must be reconciled with the Act's confidentiality provision, and to publish sector financing, geographic distribution, repayment performance, default rates, approval criteria, related-party transactions and developmental outcomes instead. It also says applicants should be told before applying what may be disclosed.
Does the Development Bank Act require the bank to publish its lending criteria?
No. Section 25 requires the bank to adopt written credit policies covering eligibility criteria, risk assessment, approval thresholds, and monitoring and recovery. No provision requires their publication, requires written reasons for a decline, or provides an appeals route.
Can the accountability measures be introduced without amending the Act?
Most can. Section 34 empowers the Minister to make regulations on the bank's operations, on the terms and conditions applicable to its loans and on recovery. The board adopts its own credit policies under section 25 and may establish committees under section 12. Penalties, a corruption offence, Bank of Guyana supervision and a nomination right to the board would each require an amendment.
What penalties does the Act impose?
A fine of not less than G$5 million and not more than G$10 million on summary conviction, applied alike to providing false or misleading information, obstruction, falsifying or destroying records, improper disclosure of confidential information, and wilfully misapplying the bank's funds. No custodial penalty is prescribed.
Is the Guyana Development Bank supervised by the Bank of Guyana?
No. Section 32 provides that the bank is not subject to the Financial Institutions Act, and section 6(a) bars it from taking deposits from the public. The Act substitutes no prudential or conduct supervision. Its external accountability runs through the Auditor General, the Minister and the National Assembly.
When does the bank open?
It begins processing applications on 5 October 2026. The Act was assented on 30 July 2026 and the commencement Order was gazetted on 17 September 2026.
Disclosure
The opinion piece of 31 July referred to above was written by Theon Alleyne, the proprietor of La Caribeña News, who is a Guyana Manufacturing and Services Association director. The Association's membership includes commercial banks that may participate in the co-financing tier described here. Statutory references are taken from Bill No. 5 of 2026 as gazetted on 4 June 2026.