By LCN Business Desk
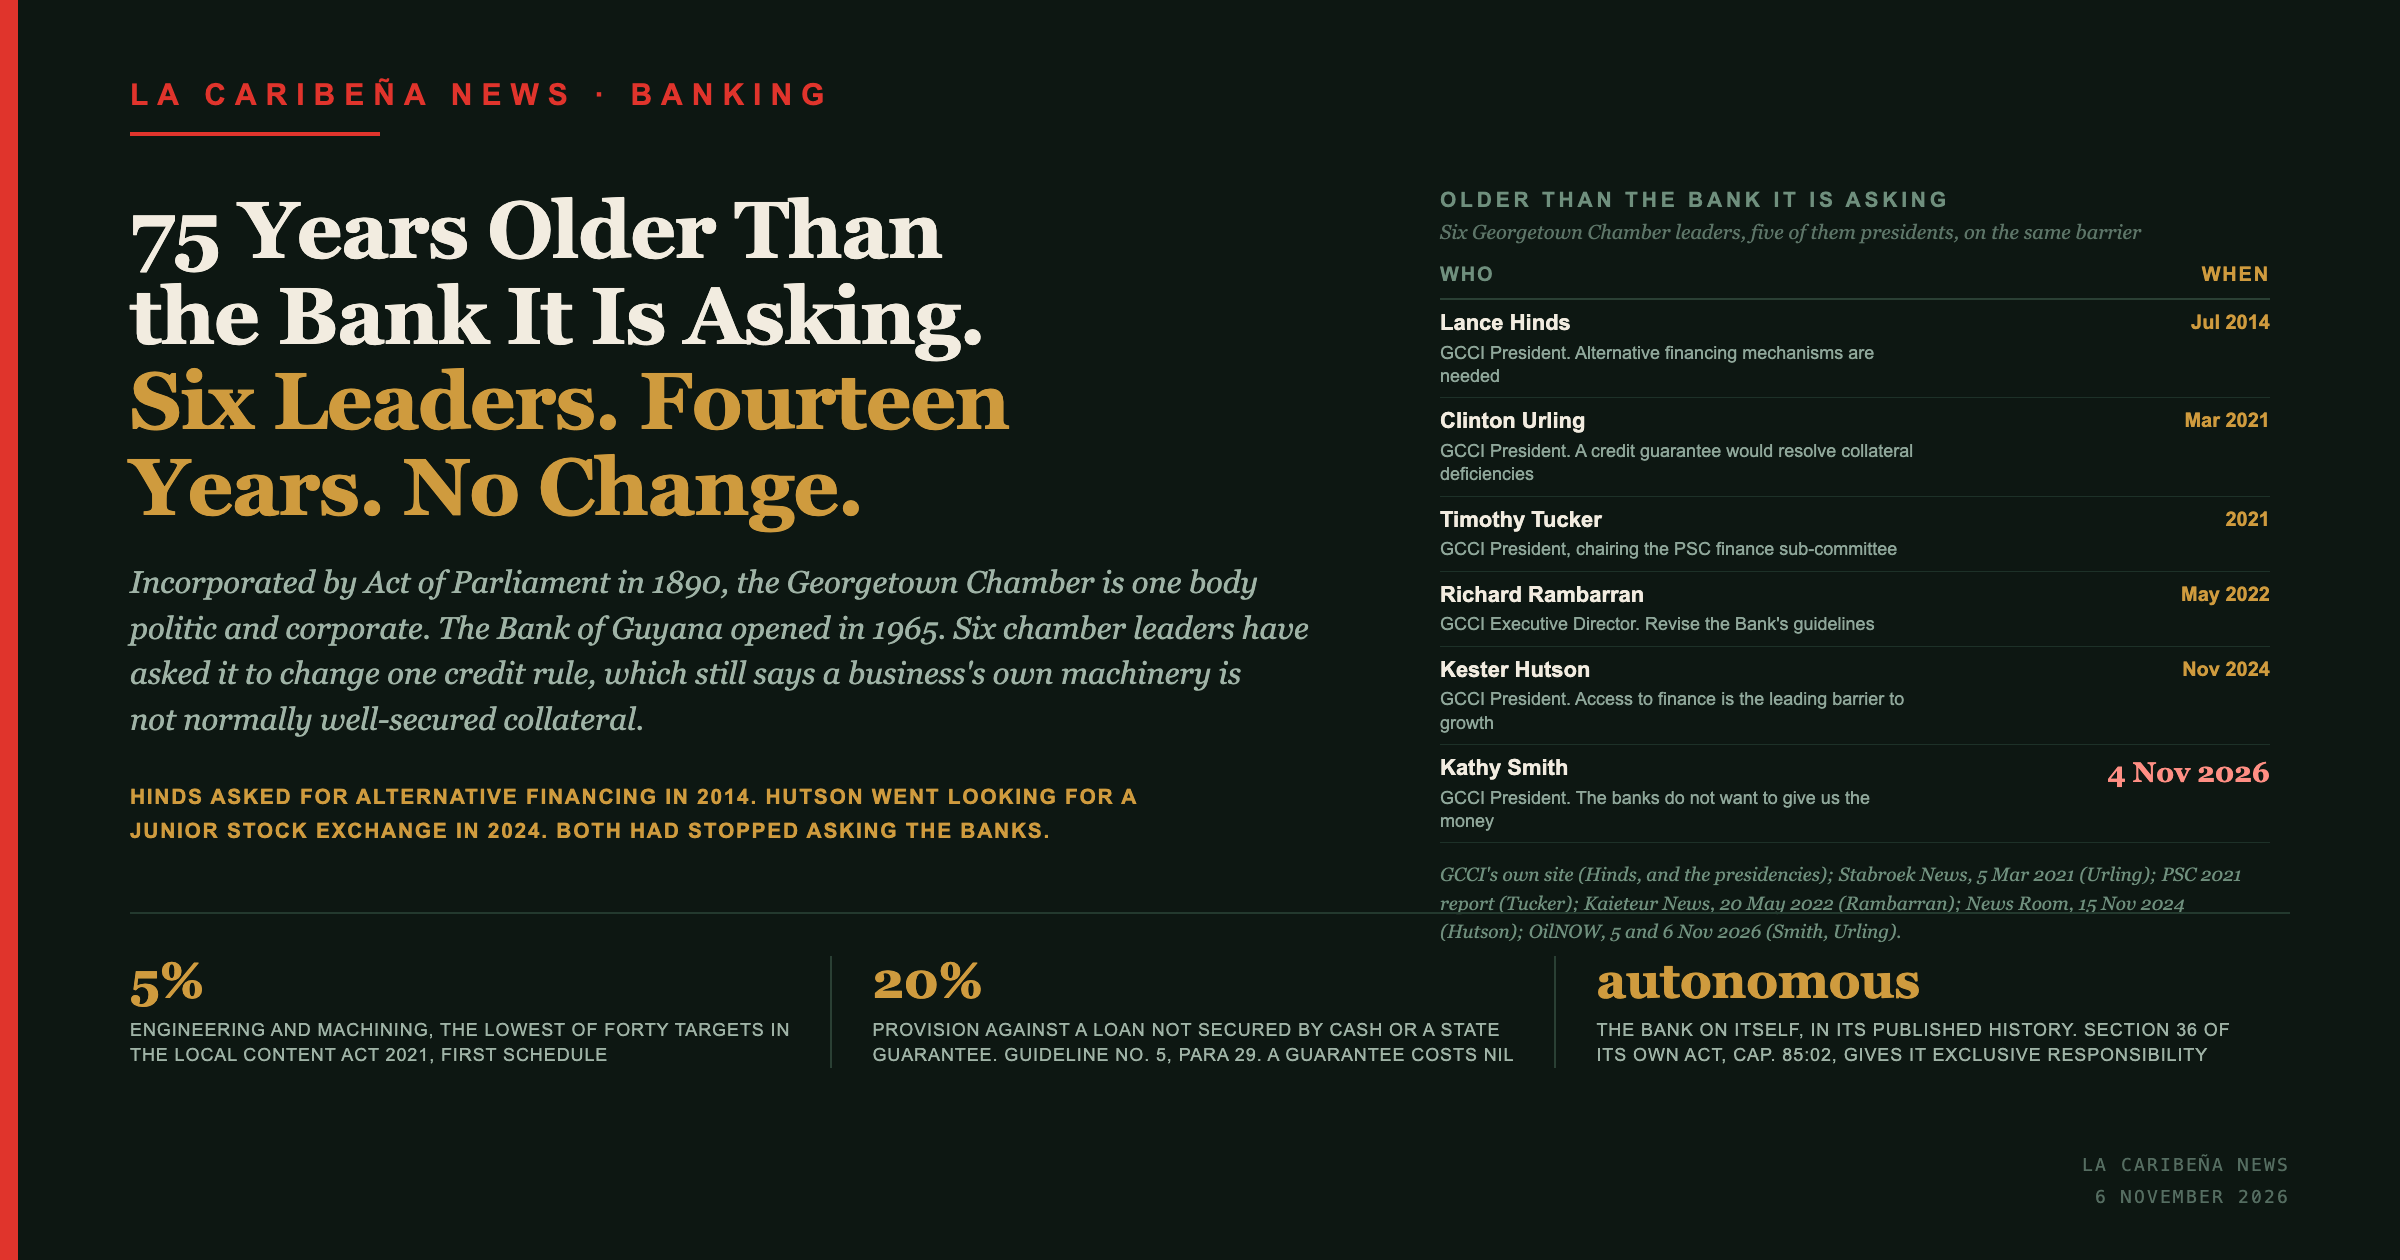
The Georgetown Chamber of Commerce and Industry Act, Cap. 89:03, incorporated the chamber on 5 February 1890. The Bank of Guyana Ordinance No. 23 of 1965 created the central bank, which opened on 16 October 1965. The chamber is seventy-five years the older institution, and it is not a trade association: its own Act makes its members one body politic and corporate, and requires its annual proceedings to be sent to a minister.
For fourteen years that body has been asking the Bank to change one rule. Six of its leaders have done the asking, five of them its president. The paragraph they are describing has not changed.
Paragraph 52 of Supervision Guideline No. 5 says specialised manufacturing facilities and equipment are not normally well-secured collateral. The guideline was revised once in those fourteen years, in July 2021, and the paragraph survived the revision.
A month ago the state opened a bank of its own to lend without collateral at all.
Who has asked Guyana to change its bank collateral rule?
Six leaders of the Georgetown Chamber of Commerce and Industry, across fourteen years.
| Year | Who | What was said |
|---|---|---|
| July 2014 | Lance Hinds, GCCI President | Not all startups and emerging businesses can go to the banks to borrow funds. Alternative financing mechanisms are needed |
| March 2021 | Dr. Clinton Urling, GCCI President 2012 to 2014 | A government-backed credit guarantee would resolve the matter of collateral deficiencies, and the Bank of Guyana's requirements could be eased for banks that lend to small businesses |
| 2021 | Timothy Tucker, GCCI President, chairing the Private Sector Commission's finance and economics sub-committee | Medium-sized businesses suffer most: not small enough for government support, not large enough for good terms from the banks |
| May 2022 | Richard Rambarran, then GCCI Executive Director | Called for a revision of the schedule guidelines the Bank of Guyana issues |
| September 2023 | GCCI and other business support organisations | Met Finance Minister Dr. Ashni Singh, Bank of Guyana Governor Dr. Gobind Ganga and the Guyana Association of Bankers |
| March 2024 | GCCI annual report | Financing remains a continuing challenge; minimum loan sizes on offer are too high for the businesses that need them |
| November 2024 | Kester Hutson, GCCI President | Access to finance is the leading barrier to business growth in Guyana and the wider region. The Chamber is exploring a junior stock market with the Jamaica Stock Exchange |
| 4 November 2026 | Kathy Smith, GCCI President | The banks and financial institutions in Guyana do not want to invest or give local businesses the money |
| 4 November 2026 | Dr. Clinton Urling again, now on the Private Sector Commission's Executive Council | Guyana needs an oil and gas development bank alongside the existing facility |
Two of the presidents reached the same conclusion a decade apart, and it was not a request to the Bank. Hinds wanted alternative financing mechanisms built, telling Stabroek Business in July 2014 that not all startups and emerging businesses can go to the banks to borrow funds. Hutson was pursuing a junior stock market through a memorandum with the Jamaica Stock Exchange. Both had stopped asking the banks to lend differently and gone looking for a way around them.
Urling made his case four months before the guideline was last revised. Writing in Stabroek News, he argued for a government-backed credit guarantee scheme in which the state would guarantee whole or partial portions of commercial bank loans. His reason was the one paragraph 52 creates: a credit guarantee, he wrote, resolves the matter of collateral deficiencies, offsets the risk of lending to small businesses and compensates for low profit margins. In the same piece he proposed easing some of the Bank of Guyana's requirements for institutions meeting an annual small-business lending quota.
Rambarran made his 2022 call as the Chamber's Executive Director, an office that carries ex-officio membership of the executive. He told Kaieteur Radio's Guyana's Oil and You that the interest-rate differential against Trinidad alone was enough to wipe out a local company's profitability, and that there could be no successful local content regime without cheaper finance for the businesses the Act was written for.
What does Guyana's central bank collateral rule actually say?
That a business's own machinery is not good security.
Guideline No. 5 is issued under Part IX, section 61 of the Financial Institutions Act 1995. Paragraph 52 reads:
"Collateral such as specialized manufacturing facilities and equipment for ongoing operations which involve large-scale employment of workers would not normally be considered well-secured because of the difficulties of actual foreclosure or of disposing of the collateral in a timely manner at values sufficient to protect the financial institution from loss."
An oil services firm's principal asset is specialised equipment. A manufacturer's is its plant. Under the guideline that governs every licensed bank in the country, neither is normally well-secured.
Paragraph 47 of the same document tells banks the opposite about method:
"Collateral is a secondary source of repayment and serves as a buffer for unforeseen losses. While collateral provides some protection against losses, LFIs should not over-rely on collateral when assessing a credit exposure. The primary focus should be on the borrower's ability to service the debt."
What does it cost a bank in Guyana to lend against equipment?
Twenty cents on the dollar, where a government guarantee costs nothing.
| Classification | Minimum provision the bank must hold |
|---|---|
| Sub-standard, secured by cash, government securities or government guarantees | 0% |
| Sub-standard, everything else | 20% |
| Doubtful, secured portion | 20% |
| Doubtful, unsecured portion | 50% |
| Loss, unsecured portion | 100% |
Bank of Guyana Supervision Guideline No. 5, paragraph 29. A general provision of at least 1 per cent applies to the un-reviewed portfolio under paragraph 30.
Paragraph 53 names what does count: irrevocable guarantees issued by first class banks, other licensed institutions and multinational companies. A Guyanese contractor with a signed contract and a yard full of equipment is not on that list.
The rule asks banks not to lean on collateral, and then prices collateral so heavily that leaning on it is the rational choice.
Where are Guyana's banks actually lending?
Into personal loans and mortgages, because they are backed by collateral, and barely into engineering.
Over the two years to December 2025, on the Bank of Guyana's own annual report, credit to the private sector grew 41.4 per cent. Personal lending grew 71.1 per cent and real estate mortgages 44.1 per cent. Credit to construction and engineering grew 13.1 per cent, the slowest of any sector the Bank names, and it fell outright in 2024.
Across the same two years the banking system's average excess liquid assets, the money held above the regulatory requirement, rose from G$148.9 billion to G$390.1 billion. Customer deposits reached 202.4 per cent of the loan book. The capital adequacy ratio stood at 18.5 per cent against a minimum of 8.0, and non-performing loans fell to 1.5 per cent of total loans.
Nothing in that picture is a banking system in trouble. It is a banking system lending where the rule makes lending cheapest.
The law points the same way. The Local Content Act 2021 reserves forty services for Guyanese firms and sets a minimum level for each. Catering, janitorial services, office rental and laundry sit at 90 per cent, and customs brokerage, local insurance and ground transportation at 100. Engineering and Machining is set at 5 per cent, the lowest figure in the schedule, and subsea work appears nowhere in it. The sector the law reserves least is the sector the banks have financed least.
Why did Guyana create a development bank?
To lend without collateral, which is what the commercial rule discourages.
The Guyana Development Bank opened on 5 October 2026 lending up to G$3,000,000 at zero interest and without collateral. It asks what an applicant can build rather than what they own, as this newspaper reported at its opening.
Paragraph 47 already gives the commercial banks that same instruction.
The new institution's first tranche is G$20 billion, funding about 6,666 loans against 15,000 to 20,000 applications, and one month in it has published no count of loans approved and no split of approvals by sector. Its entire first tranche is about a twentieth of what the commercial banks were holding above their requirement in 2025.
Urling's objection at the Marriott was to the size of that answer. Smith's was that the commercial banks above it still will not move.
Can Guyana's Minister of Finance order the Bank of Guyana to change the rule?
No. Both Acts give the job to the Bank, and one of them uses the word exclusive.
Section 36 of the Bank of Guyana Act, Cap. 85:02, reads:
"The Bank shall have exclusive responsibility for the supervision and regulation of licensed financial institutions under this Act and the Financial Institutions Act."
That covers both statutes, and Guideline No. 5 is issued under the second of them.
The rule-making powers point the same way. Under section 61 of its own Act the Bank may make regulations as required from time to time to carry that Act into effect, and section 3(8) of the Financial Institutions Act extends the same power over institutions that do not take deposits from the public. The Minister appears once, in section 3(7), as a consultee on the narrow question of what counts as financial business requiring a licence.
Neither Act contains a power for the Minister to direct the Bank. There is no provision that the Minister may give directions and no clause making the Bank subject to ministerial direction. Where the Minister does appear he appoints and removes senior officers, approves certain salaries, receives the Bank's half-yearly and annual reports and appoints its external auditors. Section 48 fixes the direction of advice the other way: the Bank is adviser to the Government.
The Bank says the same of itself. Its published history records that the 1965 Ordinance established it as an autonomous institution, and that later revisions imparted greater autonomy in its constitution, administration and operations.
Nobody needs to order this change, because the body that can make it already has exclusive authority to do so, and says so. Six chamber leaders have asked over fourteen years. Dr. Ashni Singh and Dr. Gobind Ganga sat with them in September 2023. The cover page still reads 30 July 2021.
What is not established here?
Whether the guideline has ever been considered for revision and left unchanged. The Bank's board minutes are not published. Its half-yearly and annual reports to the Minister under sections 57 to 59 are where such a decision would be recorded, and the 2025 annual report does not mention it.
The entities
- Bank of Guyana Supervision Guideline No. 5 governs credit exposure review, classification and provisioning for every licensed financial institution, issued under Part IX section 61 of the Financial Institutions Act 1995 and last revised 30 July 2021. - Richard Rambarran is a Guyanese economist who was Executive Director of the Georgetown Chamber of Commerce and Industry from 2017 for five years, and later its Senior Vice President. - Timothy Tucker is a former President of the Georgetown Chamber of Commerce and Industry and chairs the Private Sector Commission's Economics, Trade & Investment sub-committee. He chaired its finance and economics sub-committee for the 2021 report. - Lance Hinds succeeded Clinton Urling as President of the Georgetown Chamber of Commerce and Industry in April 2014 and called for alternative financing mechanisms that July. - Kester Hutson was President of the Georgetown Chamber of Commerce and Industry from March 2023, and named access to finance the leading barrier to business growth in November 2024. - Kathy Smith is President of the Georgetown Chamber of Commerce and Industry and Vice-Chair of the Private Sector Commission. - Dr. Clinton Urling was President of the Georgetown Chamber of Commerce and Industry from April 2012 until March 2014 and a past Honorary Secretary of the Private Sector Commission. He called for a government-backed credit guarantee scheme in March 2021. He sits on the Commission's Executive Council and chairs the Steering Committee of its Business Support and Development initiative with the Inter-American Development Bank. He owns German's Restaurant. - Dr. Ashni Singh is Guyana's Senior Minister with responsibility for Finance. - Dr. Gobind Ganga is the Governor of the Bank of Guyana. - Bank of Guyana Act, Cap. 85:02 is Act 19 of 1998, whose section 36 gives the Bank exclusive responsibility for the supervision and regulation of licensed financial institutions. - Georgetown Chamber of Commerce and Industry Act, Cap. 89:03 is Act 3 of 1890, which incorporated the chamber as one body politic and corporate on 5 February 1890. - Bank of Guyana Ordinance No. 23 of 1965 established the central bank, which commenced operations on 16 October 1965. - Local Content Act 2021 reserves forty services for Guyanese firms, setting Engineering and Machining at 5 per cent, the lowest minimum level in its First Schedule. - Guyana Development Bank opened on 5 October 2026 lending to G$3,000,000 at zero interest and without collateral.
What the title card says
- Headline: the chamber is 75 years older than the bank it is asking, six of its leaders have asked across fourteen years, and the rule has not changed. - Years between the chamber's incorporation in 1890 and the central bank's opening in 1965: 75. - Chamber leaders who have raised it: six, five of them presidents. - Years in which they raised it: 2014, 2021, 2022, 2023, 2024 and 2026. - Provision a bank must hold against a loan secured by a government guarantee: nil. - Provision against the same loan secured by anything else: 20 per cent. - Lowest minimum local content level in the Local Content Act's First Schedule: 5 per cent, Engineering and Machining. - The Bank's own description of its standing: autonomous, with exclusive responsibility under section 36.
Frequently Asked Questions
What is Supervision Guideline No. 5?
The Bank of Guyana rule that tells every licensed bank how to classify a loan and how much capital to set aside against it. It is issued under section 61 of the Financial Institutions Act 1995 and the version on the Bank's website is dated 30 July 2021.
Why does it matter to a business owner?
Paragraph 52 says specialised manufacturing facilities and equipment would not normally be considered well-secured. If your main asset is your equipment, the rule treats a loan against it as carrying a twenty per cent provision where a government-guaranteed loan carries none.
Who has asked for it to change?
Six Georgetown Chamber leaders across fourteen years: presidents Lance Hinds in 2014, Clinton Urling in 2021, Timothy Tucker in 2021, Kester Hutson in 2024 and Kathy Smith in 2026, together with Executive Director Richard Rambarran in 2022. The Chamber also raised financing in its 2024 annual report and at a 2023 meeting with the Finance Minister and the Governor.
Has it been changed?
The guideline was revised once, on 30 July 2021. Paragraph 52 survived that revision, and four of the six chamber leaders made their case after it.
Can a minister order a change?
No. Section 36 of the Bank of Guyana Act gives the Bank exclusive responsibility for the supervision and regulation of licensed financial institutions under both that Act and the Financial Institutions Act. Neither statute contains a ministerial power of direction. The Bank can revise the guideline on its own authority.